
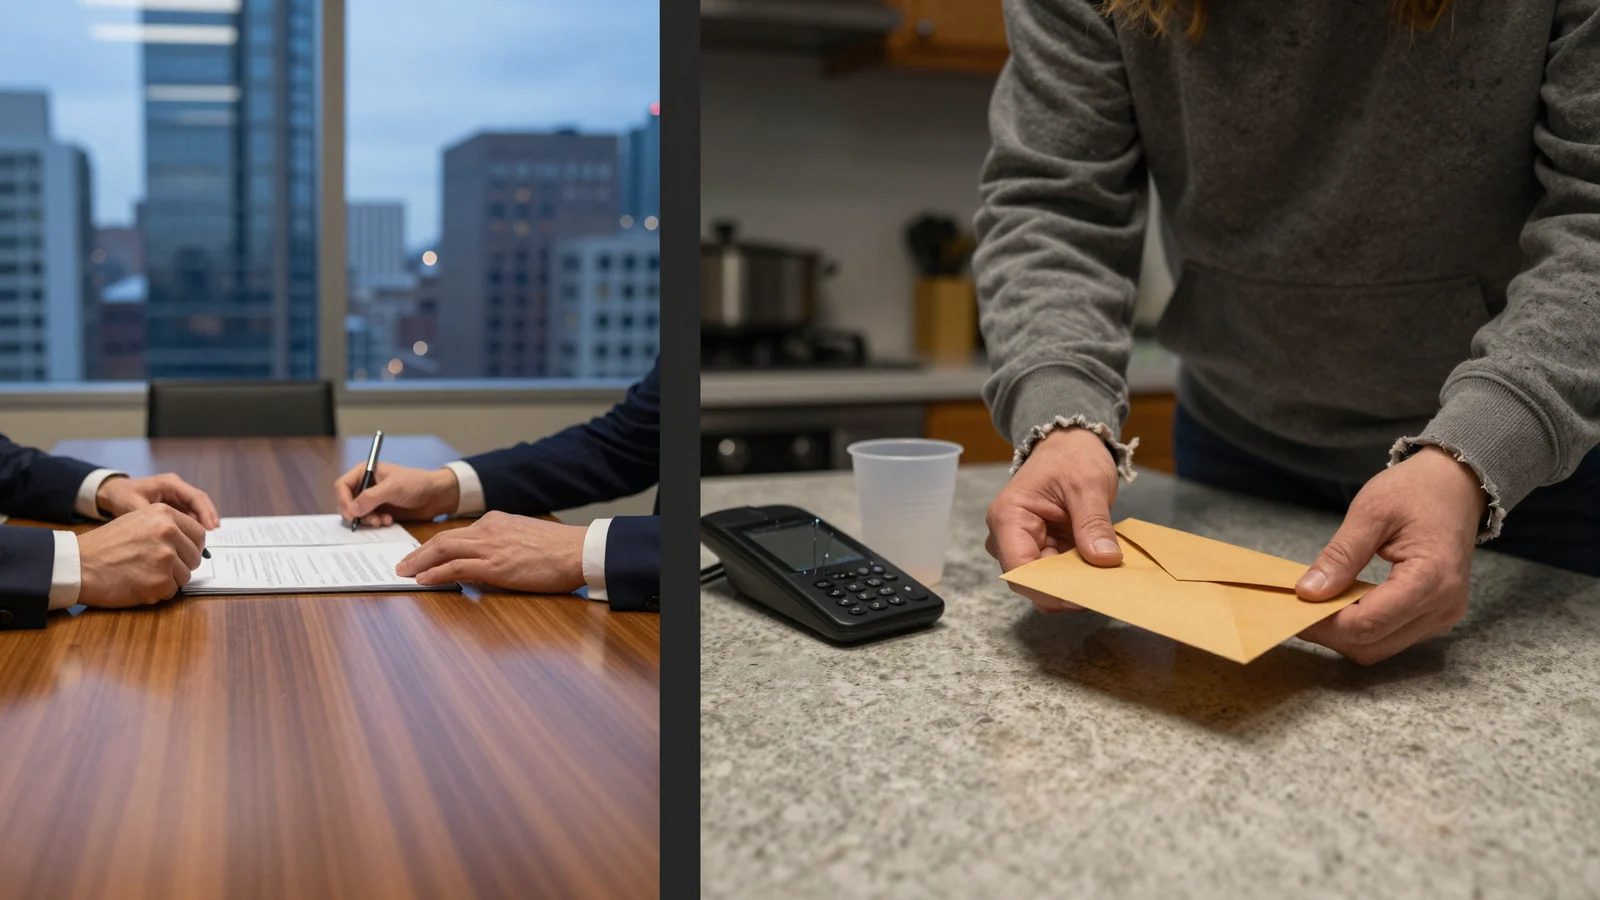
Two federal enforcement documents landed a day apart this week, and if you read them back to back you can see the whole machine.
On October 8 the Office of the Comptroller of the Currency found that American Express National Bank, from approximately June 2014 to approximately May 2025, "processed approximately $13 billion in suspected TBML activity". TBML is trade-based money laundering. Nearly eleven years. The bank's consequence is a $350 million civil money penalty, an order to submit an action plan within ninety days, and a sentence, repeated in both orders, that it "neither admits nor denies" any of it. The Federal Reserve's companion order against the parent company and a second American Express holding company carries no dollar penalty at all.
On October 9 the Department of Homeland Security and the Justice Department filed a final rule that covers, among others, people who stay in the country after being ordered out. Willfully fail to leave after a removal order and the fine is up to $998 for every day. The departments write, in their own document, that these daily penalties "can result in substantial fines, including sums of over one million dollars in certain cases".
One side negotiates. The other gets the maximum.
Here is the sentence that tells you which theory of justice applies to whom. Responding to commenters who called the fines excessive, the departments wrote that, even if the penalties were considered fines under the Constitution's Excessive Fines Clause, "DHS's decision to impose the maximum amount authorized by Congress without considering each alien's individual reasons for unlawful entry or failure to depart after a removal or departure order is neither excessive nor unconstitutional." Elsewhere they describe it as "a uniform practice of assessing the maximum statutorily authorized penalty amount in each case".
Read that again next to the bank. The bank's penalty was negotiated. It consented. Its orders provide for extensions. By my arithmetic, $350 million is about 2.7 cents for every dollar of what the OCC calls suspected trade-based money laundering activity. Nobody at the OCC wrote that the bank's individual reasons don't matter. The entire document is the bank's individual circumstances, worked out with the bank.
The person gets the maximum, and the maximum is policy.
Process is a privilege
Look at what each side gets to defend itself.
American Express gets lawyers, a consent process, ninety days to write plans, an independent consultant and a Federal Reserve press release that says "among other things". The person gets a Form 281 that DHS may serve by regular mail, and the document says that service "is complete upon mailing". From the date of service there are 15 business days to get an appeal postmarked, and the evidence generally has to go in with it. The appeal goes to another DHS officer. There is no appeal to the Board of Immigration Appeals. Before the interim version of this rule, the departments acknowledge, a person generally had 30 calendar days to answer and "could submit supporting evidence at an in-person hearing, if requested." That hearing is gone.
The departments received 28 comment submissions, and by their account "the vast majority of commenters opposed all or part of" the interim rule. The final rule's one concession: ICE will accept a late appeal if it finds that a documented mail delay beyond your control made it late. A federal court in Massachusetts stayed the interim rule "and all fines issued thereunder" in an order dated September 30; the departments date the entry of that stay to October 5. Four days after that, the final version was filed anyway, effective the day it publishes. The departments' own words: the stay "does not change the Departments' determination" that the rule can take effect immediately.
It is not one week. It is the pattern.
I keep a public case file of consumer-protection enforcement, and the same sentence shows up in it again and again. Kochava, the data broker the FTC sued over location data: the defendants "neither admit nor deny" the complaint's allegations. Cleo AI, the cash-advance app the FTC alleged misled its customers: the company "neither admits nor denies". This week the FTC announced it is sending more than $15.8 million to 2,124,796 Cleo customers who paid for eligible instant cash advances. By my count that is a little over seven dollars each, on average.
A company that settles keeps its story. The record will say forever that nothing was admitted. A person under this rule does not get that sentence. They get the maximum by default, a mailbox for a courtroom, and a deadline counted in business days.
What I think should change
Any settlement over a set size should require an admission of the facts the government found, or the government should take it to trial. "Neither admits nor denies" should be something a company earns in a small case, not something it buys in a large one.
Daily penalties on people should be individually assessed, with an in-person hearing on request and an appeal to a body that is not the agency collecting the fine. If a regulator can spend months weighing a bank's circumstances, an agency can weigh a person's reasons before fining them a million dollars.
I built this to read the documents nobody puts side by side. Read alone, each of these orders sounds like routine government business. Read together, they describe two countries. In one, a balance sheet gets a conversation. In the other, a person gets a postmark.
Source links
- OCC news release 2026-87, October 8, 2026
- OCC cease-and-desist order, AA-ENF-2026-46 (PDF)
- OCC civil money penalty order, AA-ENF-2026-47 (PDF)
- Federal Reserve Board order, Docket No. 26-052-B-HC (PDF)
- Federal Reserve Board press release, October 8, 2026
- DHS and EOIR final rule, FR Doc. 2026-21024, public-inspection copy (PDF)
- Stay order, Maria L. v. Mullin, D. Mass. No. 25-13471, September 30, 2026 (PDF, CourtListener RECAP copy)
- FTC, refunds to Cleo AI customers, October 8, 2026
- FTC v. Cleo AI, Inc., stipulated order, executed copy posted by the FTC (PDF)
- FTC v. Kochava, Inc., stipulated order, D. Idaho, filed June 25, 2026 (PDF)
- Case file: consumer-protection enforcement
- Reporting: the American Express orders
- Reporting: the immigration civil-penalties rule